Igor Kuznetsov

PhD Candidate in Finance
London Business School

I study how investors interpret information and form expectations, how these expectations relate to their allocation of capital, and how individual decisions aggregate into asset prices.

I am on the 2026–27 academic job market.

Research interests: Empirical Asset Pricing, Behavioural Finance, Machine Learning

Curriculum vitae (PDF) Research

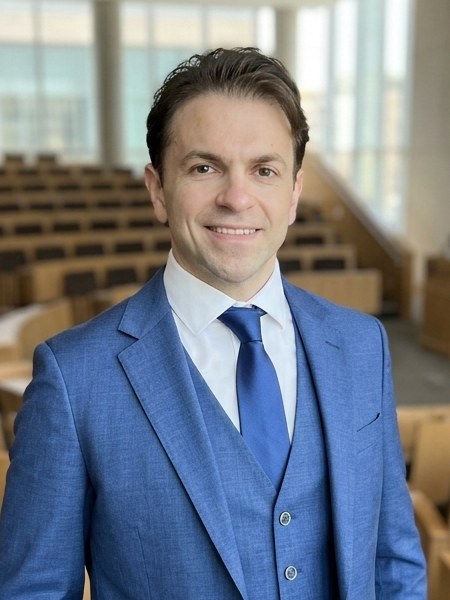
Portrait of Igor Kuznetsov

Research

Job Market Paper

There Is Something in the AirRecovering Expectations from Public Interviews with Mutual Fund Managers

Solo authored

I measure individual U.S. mutual fund managers' expectations from television interviews during 2012–2025 and link them to the portfolios they manage. Within managers, greater stated optimism about the U.S. stock market is associated with increased market exposure through trading. Allocation funds shift toward U.S. equities, while equity funds shift toward higher-beta stocks. Funds also increase positions in industries and stocks their managers discuss favorably, with stock purchases continuing after the interview. Managers extrapolate past returns at every forecast horizon, yet the difference between long- and short-horizon sentiment is countercyclical and predicts subsequent increases in portfolio beta. Managers differ persistently in their optimism and responses to market conditions, and these differences are reflected in portfolio adjustments. Public interviews thus reveal subjective beliefs that correspond to how professional investors allocate capital.

Working Papers

Do Market Prices Reflect Biased Information? Evidence from Voluntary Corporate Disclosures

with Marco Grotteria and Roberto Gómez-Cram

Using a high-frequency identification approach, we establish stock prices don't fully incorporate biased information. We study the announcements of easily quantifiable value-relevant news during voluntary corporate disclosure events where bias has been widely documented. For a large cross-section, we observe that market prices move in the same direction when the manager communicates cash-flow projections and when the same estimates are repeated by analysts the day after. Our findings are consistent with models in which investors have a heterogeneous interpretation of managerial announcements due to unknown reporting bias. We discuss alternative explanations and the implications of our results for market efficiency.

Symbolic Regressions: Opening the Black Box of Equity Premium Predictions

Predicting the aggregate equity premium remains a central challenge in asset pricing because standard financial predictors often fail out of sample. I use deep symbolic regression to identify parsimonious nonlinear models linking excess market returns to prices, dividends, earnings and risk measures. Simulations show that the method can recover the true functional form of the data-generating process with sufficient data and appropriate regularization. In monthly U.S. data from 1927 to 2021, a parsimonious model produces lower out-of-sample forecast errors than linear and tuned random-forest benchmarks. Greater complexity improves in-sample fit but generally weakens forecasts. Predictive accuracy also varies across economic episodes: some specifications perform well during the Great Recession but poorly during the pandemic.

Work in Progress

Agent-Based Trading and Price Discovery

with Svetlana Bryzgalova and Vicente Garcia

Teaching

London Business School

CourseTeaching assistant toYears
PhD
Empirical Asset PricingSvetlana Bryzgalova2022–present
MBA and Masters
Asset ManagementSvetlana Bryzgalova2022–present
Capital StructureChristopher Hennessy2023–present
Distressed InvestingChristopher Hennessy2023–present
Finance IAlex Edmans2024
Investment FundamentalsRoberto Gómez-Cram2024
InvestmentsMarco Grotteria2023

Contact

Email
ikuznetsov@london.edu
Address
London Business School
Regent's Park, London NW1 4SA
United Kingdom
Links
LBS profile · LinkedIn · GitHub